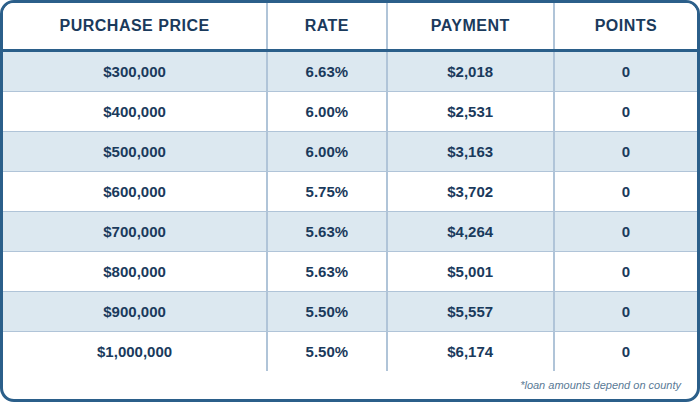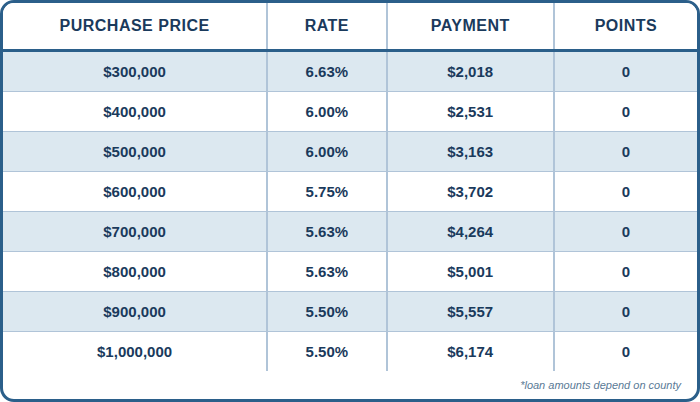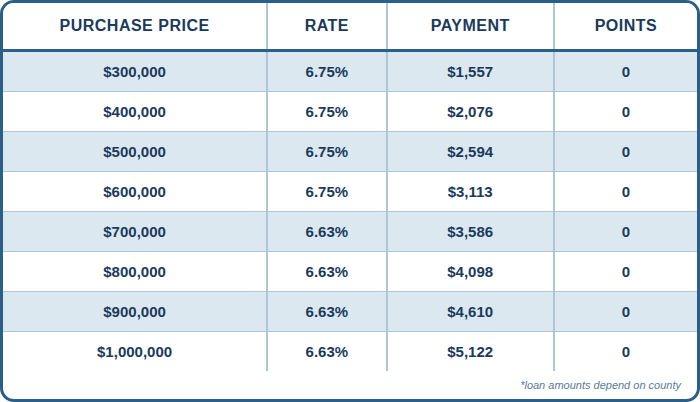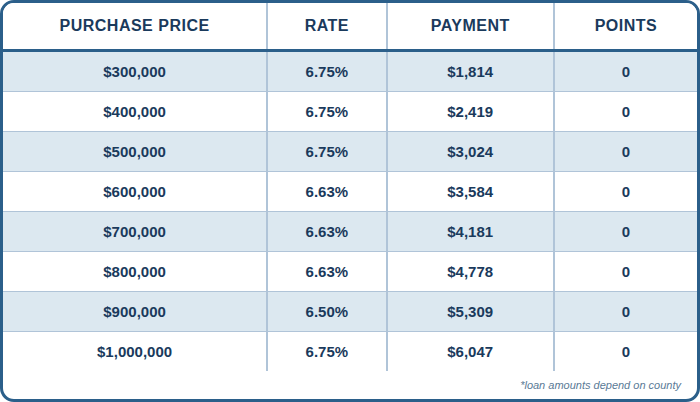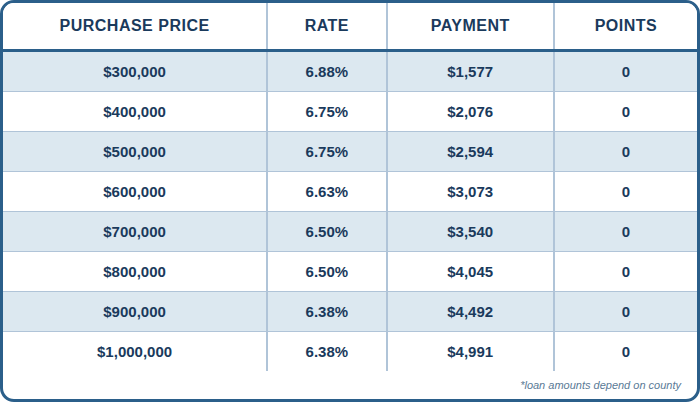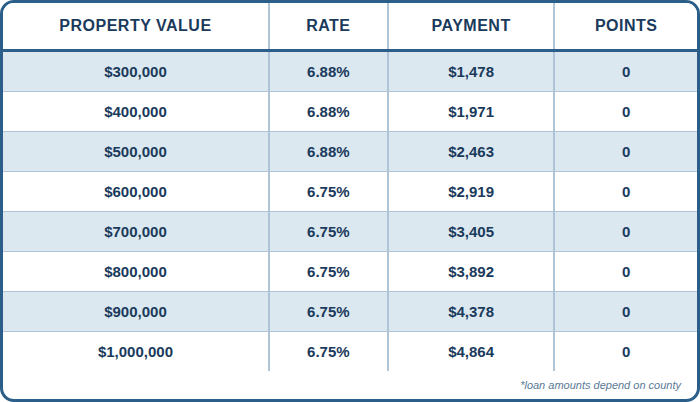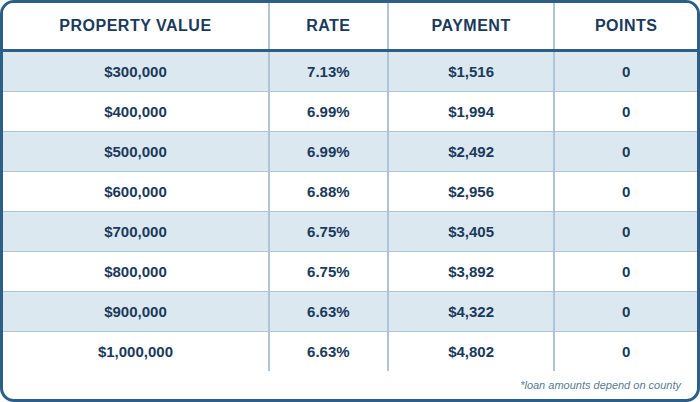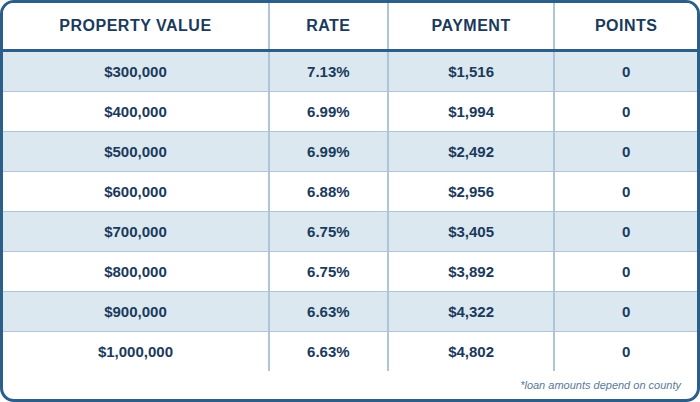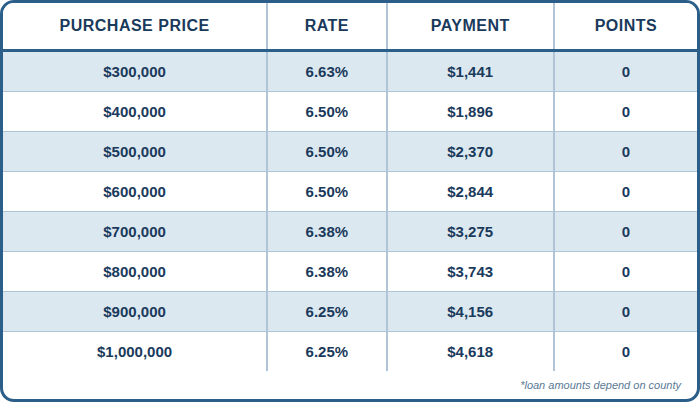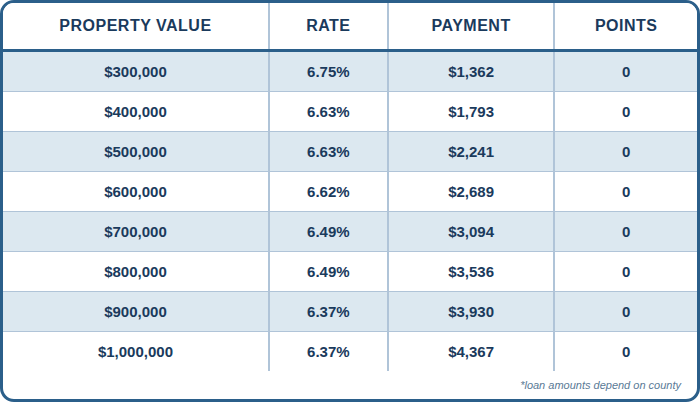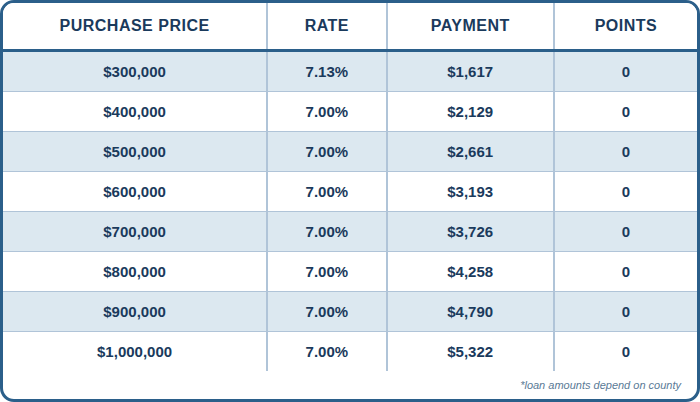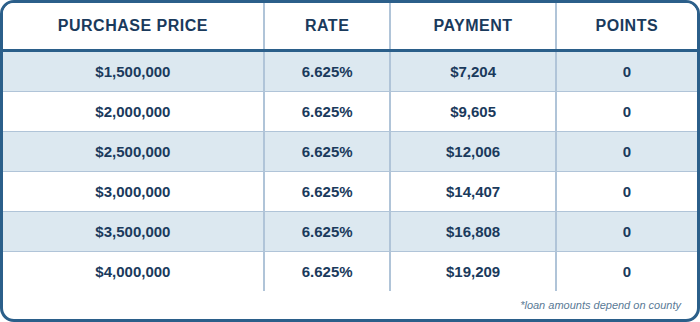
Published September 7, 2026 · Original AREG chart · Not a live quote
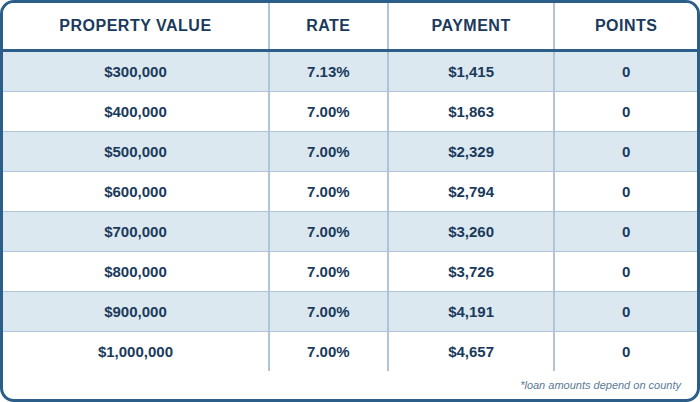
| Purchase price | Rate | Published payment* | Points |
|---|---|---|---|
| $300,000 | 6.00% | $1,898 | 0 |
| $400,000 | 5.99% | $2,528 | 0 |
| $500,000 | 5.99% | $3,160 | 0 |
| $600,000 | 5.88% | $3,749 | 0 |
| $700,000 | 5.88% | $4,374 | 0 |
| $800,000 | 5.88% | $5,126 | 0 |
| $900,000 | 6.00% | $5,838 | 0 |
| $1,000,000 | 6.00% | $6,487 | 0 |
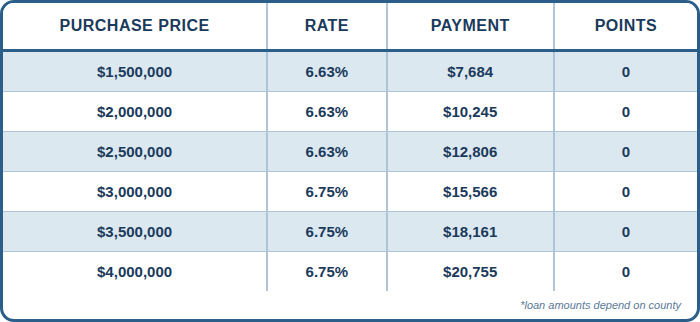
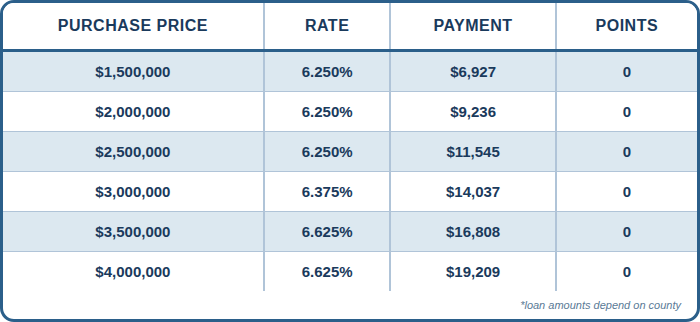
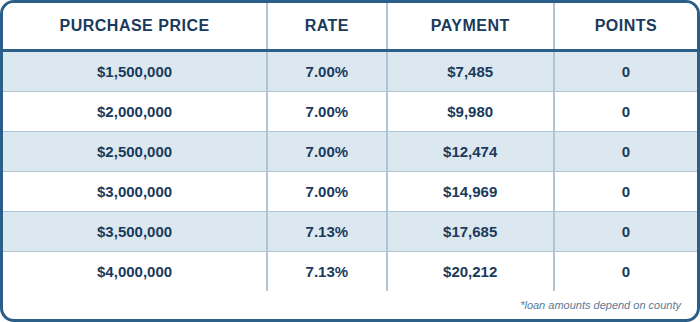
*Payment figures are copied from the source chart, not recalculated. The source does not provide a complete breakdown of taxes, insurance, mortgage insurance, or other charges. Loan amounts depend on county; request the full payment and current APR.
View the original published chart
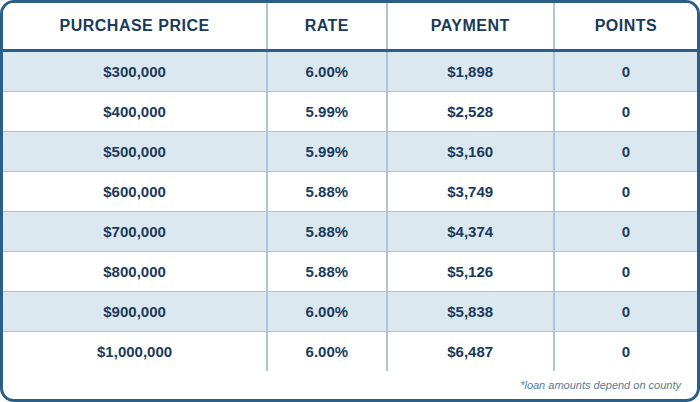
Source figures are reproduced as published. APR, lock period, and a complete payment breakdown are not supplied in this chart. Request current pricing and full terms before making a financing decision. ARM rates and payments may change after the initial fixed period.
No points · No processing fee · No underwriting fee · Up to $600 appraisal credit on purchase loans
FHA loan underwriting documents
Common starting documents — your final checklist may differ.
- Recent pay stubs and W-2s for employment income; tax returns and business information when qualifying with self-employment income.
- Bank statements showing available funds, plus documentation for the source of the down payment.
- Signed purchase agreement and any required FHA transaction forms supplied by the lender.
- Gift documentation if applicable, and explanations or records requested for credit or employment gaps.
- The lender arranges the FHA appraisal and identifies any property-related conditions.
This is a full-documentation starting list. FHA Streamline refinances have a different documentation path; ask the team before gathering a full income package.
Have government-issued identification ready. Ask the team for a secure upload link; do not email tax returns, bank statements, or identification.